What is 7Harvests ?
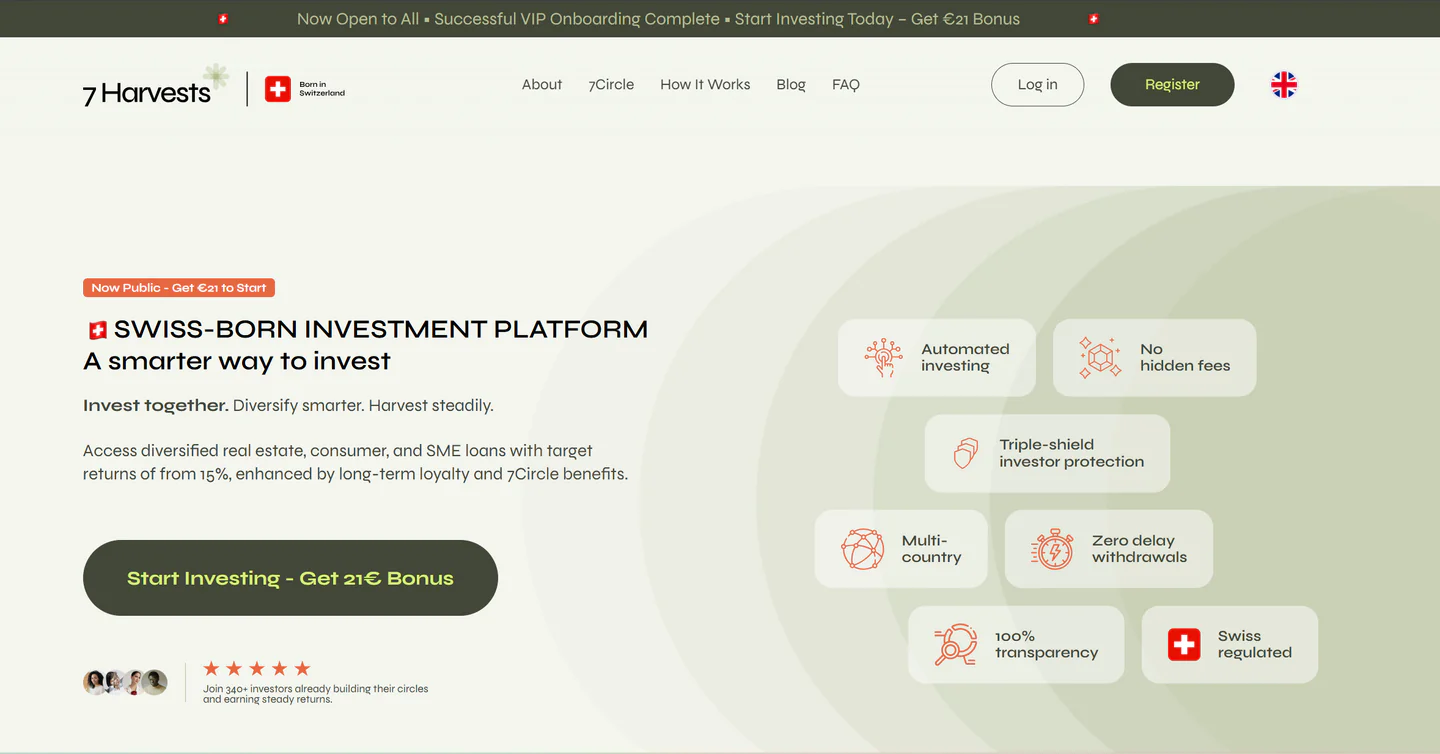
7Harvests is a peer-to-peer lending platform based in Switzerland that connects investors with European borrowers, mainly businesses but also potentially individuals. Starting from 50 €, investors can finance consumer, SME and real estate loans, backed by a two-layer buyback obligation, and receive monthly interest payments.
Company 7 Harvests AG
7 Harvests AG is a Swiss company limited by shares based in Zug, founded in April 2024 and registered under the number CHE-356.409.118, with a share capital of 100,000 CHF. Its registered purpose covers the technological development and management of advertising technologies and digital assets, along with fiduciary and financial transactions.
Originally registered as Toucan Technology Solutions AG, this fintech software development company was specialised in P2P lending platform infrastructure. It was acquired and renamed 7 Harvests AG in March 2026, with a new board appointed the same month. The platform went live in May 2026.
Regarding regulation, 7 Harvests AG is currently in the application process for becoming a member of the VQF (Verein zur Qualitätssicherung von Finanzdienstleistungen), a FINMA-recognised Self-Regulatory Organisation under Switzerland’s Anti-Money Laundering Act.
Shareholder / Founder
Ričardas Vandzinskas is the founder and chairman of the board of 7 Harvests AG. He started his career in audit at KPMG and PwC, then became CFO of Kaunas International Airport in 2008. He later served as group CFO for Hoptrans, FIMA and Ruptela, and as Chief Investments Officer at Skyways Technics.
In the P2P lending field, he joined Aventus Group in 2020, the group behind most of PeerBerry‘s loan originators. He then co-founded Hive5 in 2022 with Andrius Rupšys, CEO of Ruptela, ran it as CEO and held 35% of the holding Hive Finance, until he sold his stake to Ruptela Group in 2025.
Beyond his role as chairman, he invests his own money in the loans listed on the platform, an alignment he describes as a personal decision rather than a company policy. As the founder of 7Harvests, he may hold the entire share capital or share it with other investors, Swiss law not requiring stock corporations to publish their shareholding.
How does 7Harvests work ?
7Harvests is a P2P marketplace
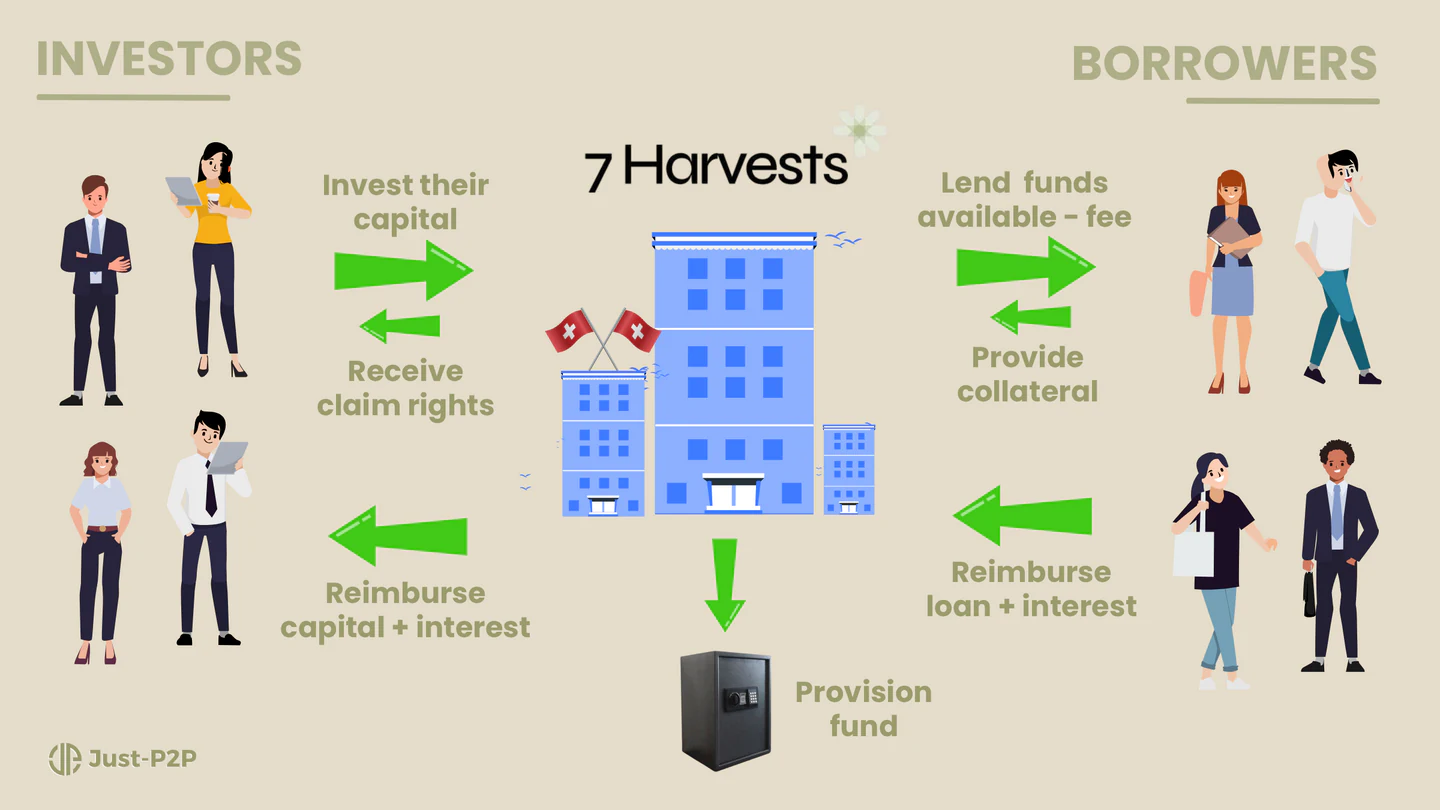
7Harvests operates as an intermediary between borrowers and investors. The platform signs the loan agreement with the borrower itself, then assigns the resulting claim to the investors who funded it, through a Claim Purchase and Assignment Agreement. As a result, investors hold a claim against the borrower rather than against the platform.
Once a project is fully funded, the platform transfers the loan amount to the borrower, minus a success fee and an allocation to a provision fund. Should a borrower fall behind, this fund covers the interest payments due to investors.
7Harvests also acts as collateral agent on behalf of investors, collecting repayments, distributing them and enforcing security when needed. Investors are therefore represented by the platform in any enforcement action. Projects raising 1 million CHF or more cannot be listed without additional regulatory measures.
Borrowers and loan selection
7Harvests advertises consumer, SME and real estate loans across several markets, granted to European individuals and businesses pursuing a clear business objective. Interest rates charged to borrowers range from 7% to 15% per year. So far, the first loan listed on the platform is a business loan.
Before a project is listed, 7Harvests reviews the borrower’s history, financial solvency, business plan and repayment schedule. Background checks are run on its management and beneficial owners. Access to registers and third-party databases is also granted for the whole duration of the project.
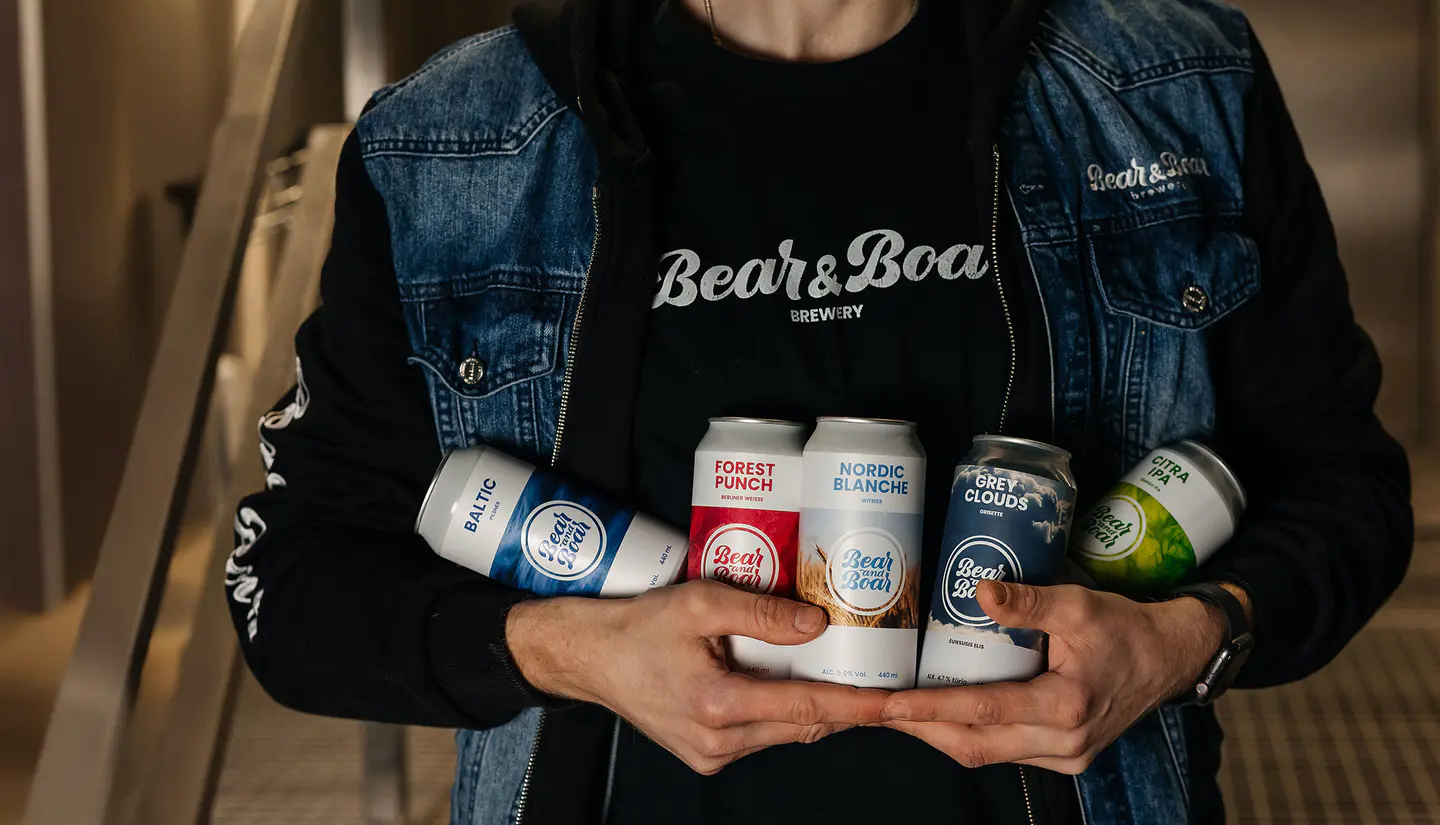
The first project listed on the platform is Lithuanian craft brewery Bear and Boar, raising 250,000 € over 12 months for refinancing and working capital, after completing a tenfold capacity expansion in 2024. Security for this first tranche rests on the founders’ personal guarantees, with full collateral announced for the next one.
Investing on 7Harvests
Who can invest ?
To invest on 7Harvests, investors must be at least 18 years old and complete an identity verification by SumSub. Both individuals and companies can open an account, the latter providing a commercial register extract, evidence of the representative’s authority and the identity of its beneficial owners.
The General Terms and Conditions are written for users residing or established in Switzerland, and investors based elsewhere confirm on registration that they approached the platform themselves. US citizens are not eligible.
The interface is available in English only, while the website welcomes investors from most countries, subject to local regulations. Adding German, French and Spanish versions would help the platform reach the largest communities of European P2P investors.
Chronology of a P2P investment
On 7Harvests, the minimum investment per project is 50 €, for durations ranging from 6 to 60 months, and total contributions per investor are capped at 100,000 CHF. Advertised returns reach up to 15% per year, with the exact rate, term and repayment schedule displayed on each listing before investing.
The repayment structure is defined project by project, on the basis of either a bullet loan or an annuity schedule. In the first case, interest is paid monthly and the principal returned at maturity, while the second combines interest and amortisation in each instalment.
Projects are generally listed for 30 days, a period borrowers can extend subject to the platform’s approval. Interest starts accruing on the day the project is successfully funded, and payments are made monthly unless the listing specifies otherwise.
Should a borrower fall more than 3 days behind, 7Harvests keeps paying the interest due to investors from its provision fund. This mechanism is designed to shield investors from short delays, and it runs until the borrower resumes payments or the fund allowance is exhausted.
Beyond 30 days, a soft collection process begins to identify a solution with the borrower. After 60 days, the platform initiates legal proceedings and enforces the collateral, and the buyback obligation applies with the loan repurchased in full, including accrued interest.
Conversely, if a borrower repays the loan early, investors receive their principal and all accrued interest. In such a case, the minimum period for which interest is paid remains three months, even when the loan is settled sooner. Investors then find these amounts credited to their account balance, ready to be reinvested or withdrawn.

Getting started
Registering on 7Harvests requires a name, a phone number and an email address. Investors can then start the identity verification process, which generally takes a few minutes. Beyond the usual selfie, they must upload a valid identity document and a proof of address of their choice.
Then, to enable deposits and withdrawals, investors must register their bank account by transferring a small amount to their 7Harvests account. Deposits start from 50 € and are made by SEPA transfer, credited within one to two business days. No commission is charged on deposits, investments or withdrawals.
The platform currently offers a 21 € welcome bonus to new investors, credited in three steps for registering, completing the verification and making a first investment. The 7Circle referral program adds a cashback or a permanent rate boost of up to 1%, granted to both the referrer and the referred investor.
On top of the standard returns, 7Harvests has set up a loyalty program that currently applies for the whole duration of the investment. There is no additional condition beyond the amount invested (no minimum seniority is required). There are 3 levels :
- Tier 1 Seed : +1% from 1,000 € invested
- Tier 2 Growth : +2% from 10,000 € invested
- Tier 3 Harvest : +3% from 35,000 € invested

Is it safe to invest on 7Harvests ?
While waiting for its VQF membership, 7Harvests has already put several investor protections in place : a named governance structure, a two-layer buyback and segregated client funds. Nevertheless, the platform remains young, with a very short track record and limited borrower diversification.
Pros to investing on 7Harvests
Two-Layer Buyback
On 7Harvests, all loans listed on the platform are covered by a buyback guarantee. If a borrower falls more than 60 days behind, the claim is repurchased in full, including the interest accrued until that date. Before that stage, the provision fund covers the monthly interest payments from the third day of delay.
In addition, 7Harvests commits to stepping in at platform level, as Income Marketplace does with its Junior Share, for example. To back that commitment, the company maintains a cash-to-portfolio ratio of at least 10% from its own operating liquidity.
So far, the only project listed has been contracted directly by 7 Harvests AG, without any intermediate lending company standing between the borrower and the platform. Publishing the size of the provision fund and of the liquidity buffer would let investors measure the protection they benefit from.
Named Governance Structure
In a LinkedIn post published shortly after the launch, the founder named three control functions : an independent board member, an AML officer and an external auditor. Two of these appointments can be checked in the Swiss commercial register, which is more disclosure than most platforms provide at this stage.
Having designed and delivered the anti-money laundering training of the VQF since 2011, as an expert in finance and banking, Kurt Schöllhorn brings to the board a precise knowledge of what the self-regulatory organisation expects from its members.
The audit report published by 7Harvests covers the predecessor entity and is signed by two licensed audit experts of bePartner AG. A post-launch statement, once the platform has a full year of activity behind it, will be the more telling document.
Segregated Client Funds
Client money sits on an account kept separate from the platform’s own operating funds, held with Swiss banks. In a wind-down scenario, a third-party administrator would take over loan servicing and repayments would continue according to the initial schedule.
This protection covers the cash waiting on the account, not the capital already lent, which remains exposed to the borrower. Naming the bank or payment institution holding these accounts would give investors an additional point of reference.
The General Terms and Conditions are also explicit about what segregation does not provide. Client money falls outside the Swiss deposit insurance scheme and carries no preferential ranking in an insolvency, as on any P2P lending platform.
Cons to investing on 7Harvests
No Track Record
7Harvests opened to the public in May 2026, and no portfolio statistics have been published yet. Funded volumes, repayment performance and average returns are not available, which is not unusual three months after a launch, but investors have no measure of the platform’s performance to rely on today.
The quarterly financial and operational reporting announced on the homepage has not been published yet, the platform having launched only three months ago. The financial statement currently available covers the predecessor entity, before the platform started operating.
Publishing a statistics page from the start, even in a simple form, would already give investors a first reference point. Sharing figures on the projects turned down, a topic the platform has covered on its blog, would also put numbers behind the selectivity it describes.

Regulation Still Pending
Operating from Switzerland, 7Harvests falls outside the European Crowdfunding Regulation and the MiFID II framework. An EU licence would bring capital requirements, supervision by a national authority, a standardised information sheet before each project, and an appropriateness test for newcomers, as on Debitum.
Nevertheless, 7 Harvests AG is going through the application process for VQF membership, which would place it under a FINMA-recognised self-regulatory organisation on anti-money laundering matters. Swiss law imposes real obligations in that field (periodic inspection, compliance handled by a certified professional).
The founder has explained this choice, pointing to segregated investor accounts, ongoing compliance obligations and a Swiss-certified auditor. Swiss and European frameworks each have their own logic, Maclear having made the same choice, and investors will weigh what matters most to them.
Limited Diversification Options
7Harvests offers consumer, SME and real estate loans across several markets, with one business loan listed so far. Building a portfolio spread across sectors, countries and loan types will require a broader range of projects than the platform currently proposes.
The tools are already there for the day it becomes possible. The advanced auto-invest offers filters on country, loan type, term and loan-to-value ratio, and the simple automated strategy sets a diversification target of at least twenty loans.
These filters will take their full meaning once several listings run in parallel. Until then, investors spread their capital over a small number of borrowers, a stage most platforms go through in their first months. Revest shows the same type of limitation.
No Secondary Market
7Harvests announces loan terms ranging from 6 to 60 months, which investors hold until maturity. The General Terms and Conditions already provide a legal framework for a secondary market, with an assignment agreement between investors, so the feature could be activated once the platform reaches a sufficient volume.
For medium and long-term investors, this absence is not necessarily a problem. Their horizon already matches the duration of the projects listed, and the lack of a secondary market also prevents the speculation seen on platforms like Esketit, where claims are resold at a premium.
The zero delay withdrawals advertised on the homepage apply to cash sitting idle on the account, not to capital committed to a project. With terms that can reach five years, as on Lendermarket, investors will want to size their allocation accordingly.

Opinion on 7Harvests
Launched in May 2026, 7Harvests mainly offers business loans from 50 € with advertised returns of up to 15% p.a. The platform announces several protection mechanisms, among them a buyback obligation triggered after 60 days and a second layer stepping in at platform level, which time will put to the test.
Appointing a board member, a certified AML officer and an external auditor from the start is a sound signal. The first audit covers a period before the platform started operating, and publishing the work of these functions as it comes will let investors follow the governance in action.
In the same vein, securing the VQF membership will bring a first external confirmation of the platform’s compliance. Its scope covers anti-money laundering matters, so financial soundness and investor protection will be judged on the figures and the track record 7Harvests builds over the coming years.

Judging how the platform will perform is difficult with a single project listed. No portfolio statistics have been published, and the quarterly reporting announced on the homepage is still to come. A first set of figures, even minimal, would already give investors something to follow month after month.
Widening the offer is the next step. Consumer, SME and real estate loans are announced across several markets, with one business loan listed so far. A regular flow of projects across sectors and countries will let investors build the diversified portfolio the platform is designed for.
To conclude, 7Harvests has built its foundations before its track record, which seems a logical approach. The coming months will bring the elements investors are waiting for : published figures, a confirmed membership and a steady flow of projects to choose from.
